

Navigating the Challenges of Opening a Business Bank Account in Dubai: A 2026 Strategic Guide
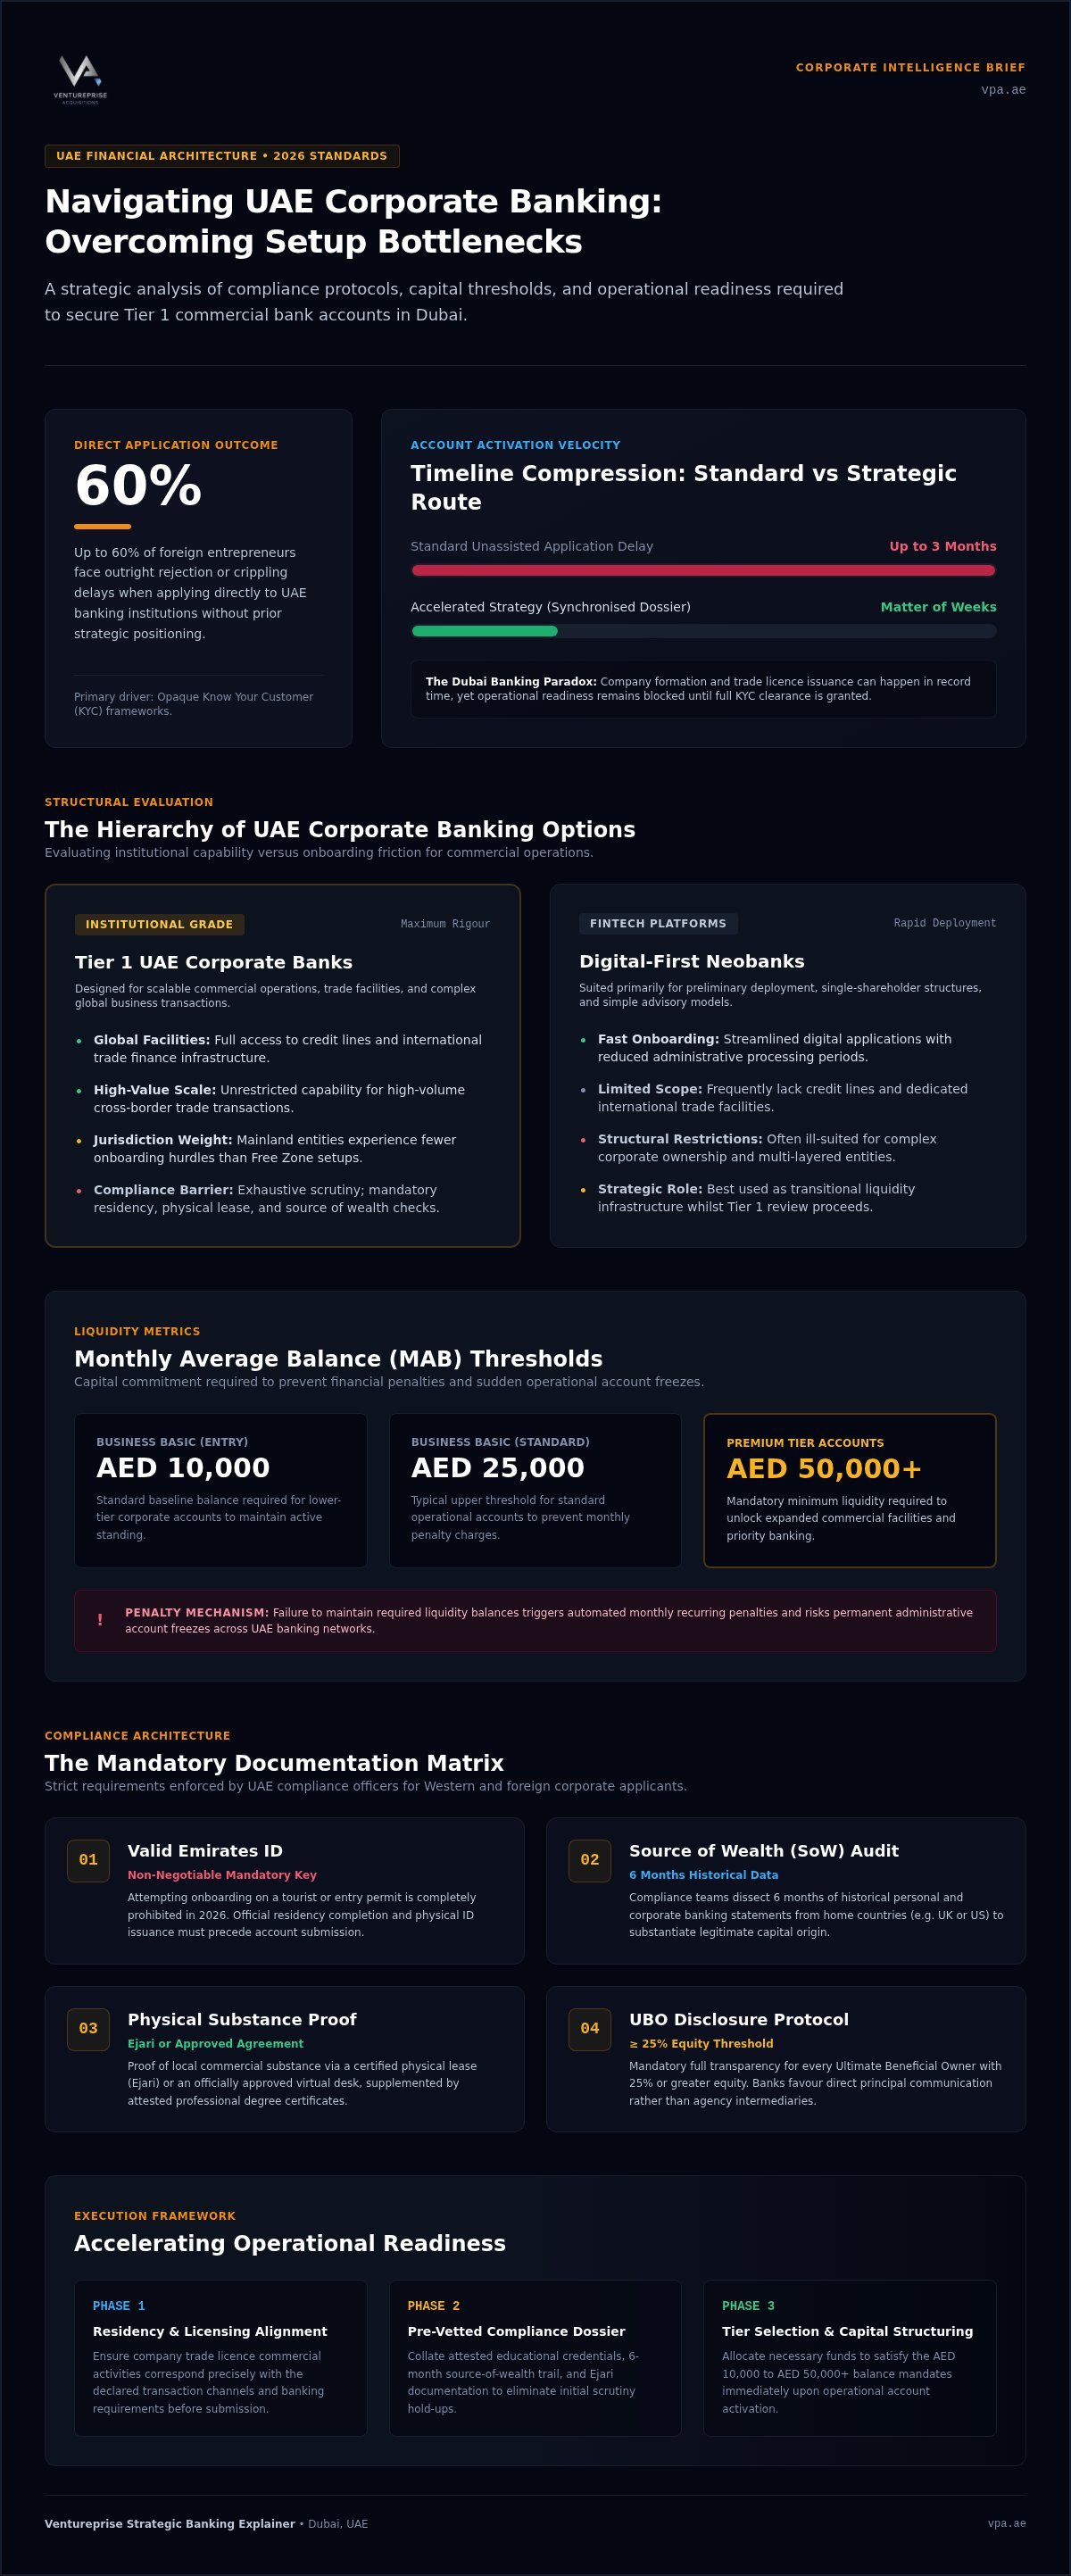
Did you know that up to 60% of foreign entrepreneurs face outright rejection or crippling delays when applying directly to UAE banks? You've secured your trade licence in record time, yet your capital remains frozen behind an opaque wall of compliance. It's a common frustration; the company is legally active, but the operational engine is stalled because you're still wrestling with the challenges of opening a business bank account in Dubai. You likely expected a seamless transition, but instead, you're met with unexpected minimum balance requirements and a KYC process that feels designed to obstruct rather than facilitate.
This guide reveals the hard truths about UAE corporate banking and the strategic manoeuvres required to secure approval without the typical three-month delay. We position banking as the critical path following your residency, ensuring you hit the ground ready to trade. You'll discover the unspoken rules used by elite strategists to bypass compliance loops and activate your account within weeks. We provide a clear path to finding a banking partner that supports international trade without the constant threat of frozen funds. It's time to stop waiting for permission and start executing your vision with an operational account that matches your ambition.
Table of Contents
The Dubai Banking Paradox: Why "Easy" Setup is a Strategic Myth
Many entrepreneurs are lured by the speed of Dubai's company formation, only to hit a wall when they realise that banking is a separate, far more rigorous battle. The myth of an unregulated, instant market is dangerous; the 2026 reality is that banks act as the ultimate gatekeepers for your commercial operations. Bankability is the most critical asset for a new Dubai entity.
The primary challenges of opening a business bank account in Dubai often arise from confusing fintech payment platforms with Tier 1 UAE corporate bank accounts. While digital apps offer rapid onboarding, they frequently lack the credit lines and international trade facilities required for high-value growth. These institutions must adhere to strict Know Your Customer (KYC) regulations, which treat every new application with deep scrutiny.
The Hierarchy of UAE Banking Options
Success starts with choosing the right tier. Tier 1 institutions offer the stability and global reach essential for large-scale operations, yet they demand the highest levels of transparency. Digital-first banks provide a faster alternative for simple consultancy models but can be restrictive for complex corporate structures. Your choice of jurisdiction also dictates your path. Mainland companies often face fewer hurdles than Free Zone entities when targeting Tier 1 partners. Explore our strategic solutions to align your setup with banking requirements.
The Minimum Balance Hurdle
Liquidity is a non-negotiable metric for UAE banks. Standard "Business Basic" accounts typically require a Monthly Average Balance of AED 10,000 to AED 25,000, whilst "Premium" tiers often jump to AED 50,000 or more. Failing to maintain these levels triggers monthly penalties and can lead to account freezes. You must structure your initial capital to satisfy these requirements immediately to demonstrate financial health and operational substance.
The Documentation Minefield: Navigating Compliance for UK and US Citizens
Navigating the paperwork required by Tier 1 banks often proves more complex than the company formation itself. For Western expats, the "Source of Wealth" (SoW) check is the most common point of failure. Banks don't just want to see your current balance; they demand a historical trail of how that capital was generated. If you're starting a company in Dubai from London, expect compliance officers to dissect six months of personal and corporate statements from your home country.
These rigorous checks represent the core challenges of opening a business bank account in Dubai. You cannot bypass the residency requirement. A valid Emirates ID is the mandatory key for Tier 1 onboarding. Attempting to open high-level accounts on a tourist or entry permit is a non-starter in 2026. Your business activity must match your banking needs perfectly to avoid immediate red flags.
Essential Paperwork Beyond the Basics
Compliance extends to your physical substance. Banks frequently request attested educational certificates to verify the professional expertise behind the business. You must also provide an Ejari (physical lease) or a government-approved virtual desk agreement. According to the International Trade Administration UAE banking guide, demonstrating local substance is vital for cross-border trade approval. Without these proofs, your application will likely stall at the first review stage.
The Role of the Ultimate Beneficial Owner (UBO)
Transparency is the standard. Banks require full disclosure of all shareholders holding 25% or more equity, regardless of the 100% foreign ownership rules. They favour direct communication with the UBO rather than third-party intermediaries to ensure your stated business activity aligns with your transaction patterns. If you're struggling to organise your dossier, our team can help you optimise your strategic planning. Reach out to our consultants today to discuss your banking requirements.
Strategising for KYC: How to Position Your Business as "Low Risk"
One of the primary challenges of opening a business bank account in Dubai is overcoming the high-risk label often attached to foreign-owned startups. You must present a business plan designed for bankers, not venture capitalists. Focus on regional risk factors and demonstrate clear, stable revenue streams. In 2026, your bank KYC will be immediately stalled if you cannot provide proof of Federal Tax Authority (FTA) registration, as compliance with the 9% statutory corporate tax is now a mandatory prerequisite for account activation.
Physical presence is non-negotiable for Tier 1 institutions. A local UAE mobile number and active SIM card are essential for your application; banks view a foreign number as a sign of a suitcase entrepreneur with no local substance. During the bank interview, be precise about international transfers. Avoid vague terms regarding cross-border flows. If you are operating in the advisory space, ensure your narrative matches our execution guide for management consulting to satisfy compliance officers.
Identifying and Mitigating Red Flag Activities
Industries such as crypto, high-value commodity trading, and general consulting face the highest scrutiny from compliance committees. To succeed, you must demonstrate local market intent. Even if your clients are primarily in the UK or USA, you must show how your Dubai office adds tangible value to the local economy. Referencing the UK government guidance on overseas business risk in the UAE can help you align your risk profile with international standards that local banks respect.
The Post-Formation Timeline
Within the Ventureprise model, banking activation begins strictly from Day 27 onwards. This sequence ensures your Emirates ID and residency are fully processed before the first formal bank meeting. Rushing this sequence is a common mistake that leads to permanent rejection. If you want to bypass these hurdles and secure an operational account, book a consultation with our banking specialists to pre-screen your compliance dossier.
The Ventureprise Path: Accelerating Your Operational Readiness
Success in the UAE isn't just about obtaining a trade licence; it's about achieving full operational liquidity. We eliminate the standard banking minefield by utilising direct liaisons and submitting pre-vetted applications. This proactive approach bypasses the typical challenges of opening a business bank account in Dubai, ensuring your file is seen by the right decision-makers from the start. We translate local bureaucracy into plain English, removing the jargon-heavy delays that stall our competitors.
Our concierge advantage bridges the gap between your physical biometrics and account activation. We don't just hand you a folder and wish you luck. Instead, we provide an elite guide to navigate the medical and biometrics appointments, followed by a direct handover to our banking partners. We manage the entire follow-up process with bank compliance teams, applying a "We Get S**t Done" attitude to every hurdle. This ensures you move from residency to trading without the friction that typically derails new market entrants.
Beyond the Account: Wealth Management and Growth
An operational corporate account is merely the foundation. To ensure long-term asset security, we integrate your business banking with sophisticated private client wealth structuring in Dubai. This strategic alignment allows you to move capital into foundations or trusts, protecting your global footprint whilst you scale your UAE operations. We treat your corporate and private interests as a unified strategy for rapid advancement.
The 27-Day Handover and Banking Activation
Once your Emirates ID is in hand, typically on Day 27, the focus shifts immediately to banking activation. Your formation paperwork is already complete, and your compliance dossier is pre-vetted and ready for submission. We don't wait for banks to call us; we drive the conversation daily. This relentless follow-up ensures that your account is active and ready for high-value deposits in weeks, not months. You focus on your commercial growth whilst we secure the strategic infrastructure that makes it possible.
Mastering Your Path to Operational Liquidity
Securing your entry into the UAE market requires more than just a trade licence; it demands a sophisticated approach to financial infrastructure. You've discovered how the challenges of opening a business bank account in Dubai stem from a fundamental paradox between rapid company formation and rigorous global compliance. Success hinges on precise KYC positioning, a robust 'Source of Wealth' narrative, and a clear demonstration of local substance. By synchronising your banking application with your residency timeline, you transform a potential three-month delay into a calculated strategic advantage.
Ventureprise Acquisitions delivers this through a proven 27-day formation and residency cycle, backed by UK-led strategic expertise and direct government liaisons. We don't just facilitate paperwork; we accelerate your operational readiness by managing the complex compliance follow-up that stalls most market entrants. It's time to cut through the banking bureaucracy with Ventureprise Acquisitions and secure the high-tier accounts your business deserves. Your vision is ready for execution. Let us build the bridge to your rapid commercial success.
Frequently Asked Questions
Why is it so difficult to open a business bank account in Dubai as a non-resident?
Opening an account is difficult because banks prioritising local residency and physical substance must satisfy strict global anti-money laundering standards. Whilst you can form a company remotely, Tier 1 banks require an Emirates ID and a physical presence to pass compliance. These hurdles represent the primary challenges of opening a business bank account in Dubai. Without a residency visa and local documentation, your application is viewed as high risk.
Do I need to buy property in Dubai to open a corporate bank account?
You don't need to purchase property to secure a corporate bank account. Residency is obtained through your business setup rather than real estate investment. Banks focus on your business model, source of wealth, and trade licence rather than your property portfolio. Buying property is a common myth that distracts from the actual requirement: demonstrating a legitimate commercial operation with a physical office or a government-approved virtual desk agreement.
How much is the minimum balance required for a Dubai business bank account?
Minimum balance requirements vary depending on the banking tier you select. Traditional Tier 1 banks typically require a Monthly Average Balance ranging from AED 10,000 to AED 50,000 for standard SME accounts. Digital neobanks often offer zero-balance options supported by a monthly maintenance fee. You must maintain these levels to avoid monthly penalties or account restrictions, making capital planning a vital step before you begin the formal application process.
Can I open a Dubai business bank account remotely from the UK or USA?
You cannot complete the entire banking setup remotely because Tier 1 institutions require a physical meeting and a valid Emirates ID. Whilst you can initiate the company formation and visa processing from the UK or USA, you must travel to Dubai for medical and biometrics registration. These steps are essential to overcome the challenges of opening a business bank account in Dubai, as physical presence is a mandatory requirement.
How long does the corporate banking setup process actually take in 2026?
The timeline depends on your business complexity and the bank you select. Digital business accounts can be active within 48 hours to 10 days once your residency is finalised. However, traditional Tier 1 commercial banks typically require four to twelve weeks for a full compliance review. Within our model, we initiate this process from Day 27 onwards to ensure all residency documents are in hand before the review begins.


Comments