

Repatriating Profits from Dubai to UK: 2026 Tax Implications for Entrepreneurs
Your Dubai success story shouldn't end with a devastating HMRC audit notice landing on your UK doorstep. Most ambitious founders assume that paying the 9% UAE corporate tax is the end of their fiscal obligations, but the reality of repatriating profits from Dubai to UK tax implications in 2026 is far more aggressive. You've built a high-value enterprise to achieve freedom, not to become a target for the Revenue's increasingly sophisticated tracking systems.
The complexity of the Statutory Residence Test and the shifting 2026 UAE tax rules often act as a professional barrier to wealth expansion. This article provides the definitive roadmap to master cross-border wealth transfer and ensure your success doesn't trigger an unnecessary tax trap. You'll gain absolute clarity on asset protection, learn how to navigate the 2026 regulatory shifts, and discover the strategic wealth-structuring frameworks that elite entrepreneurs use to maintain compliance whilst accelerating their global momentum.
Table of Contents
The 2026 Tax Landscape: Navigating UAE Corporate Tax and HMRC Rules
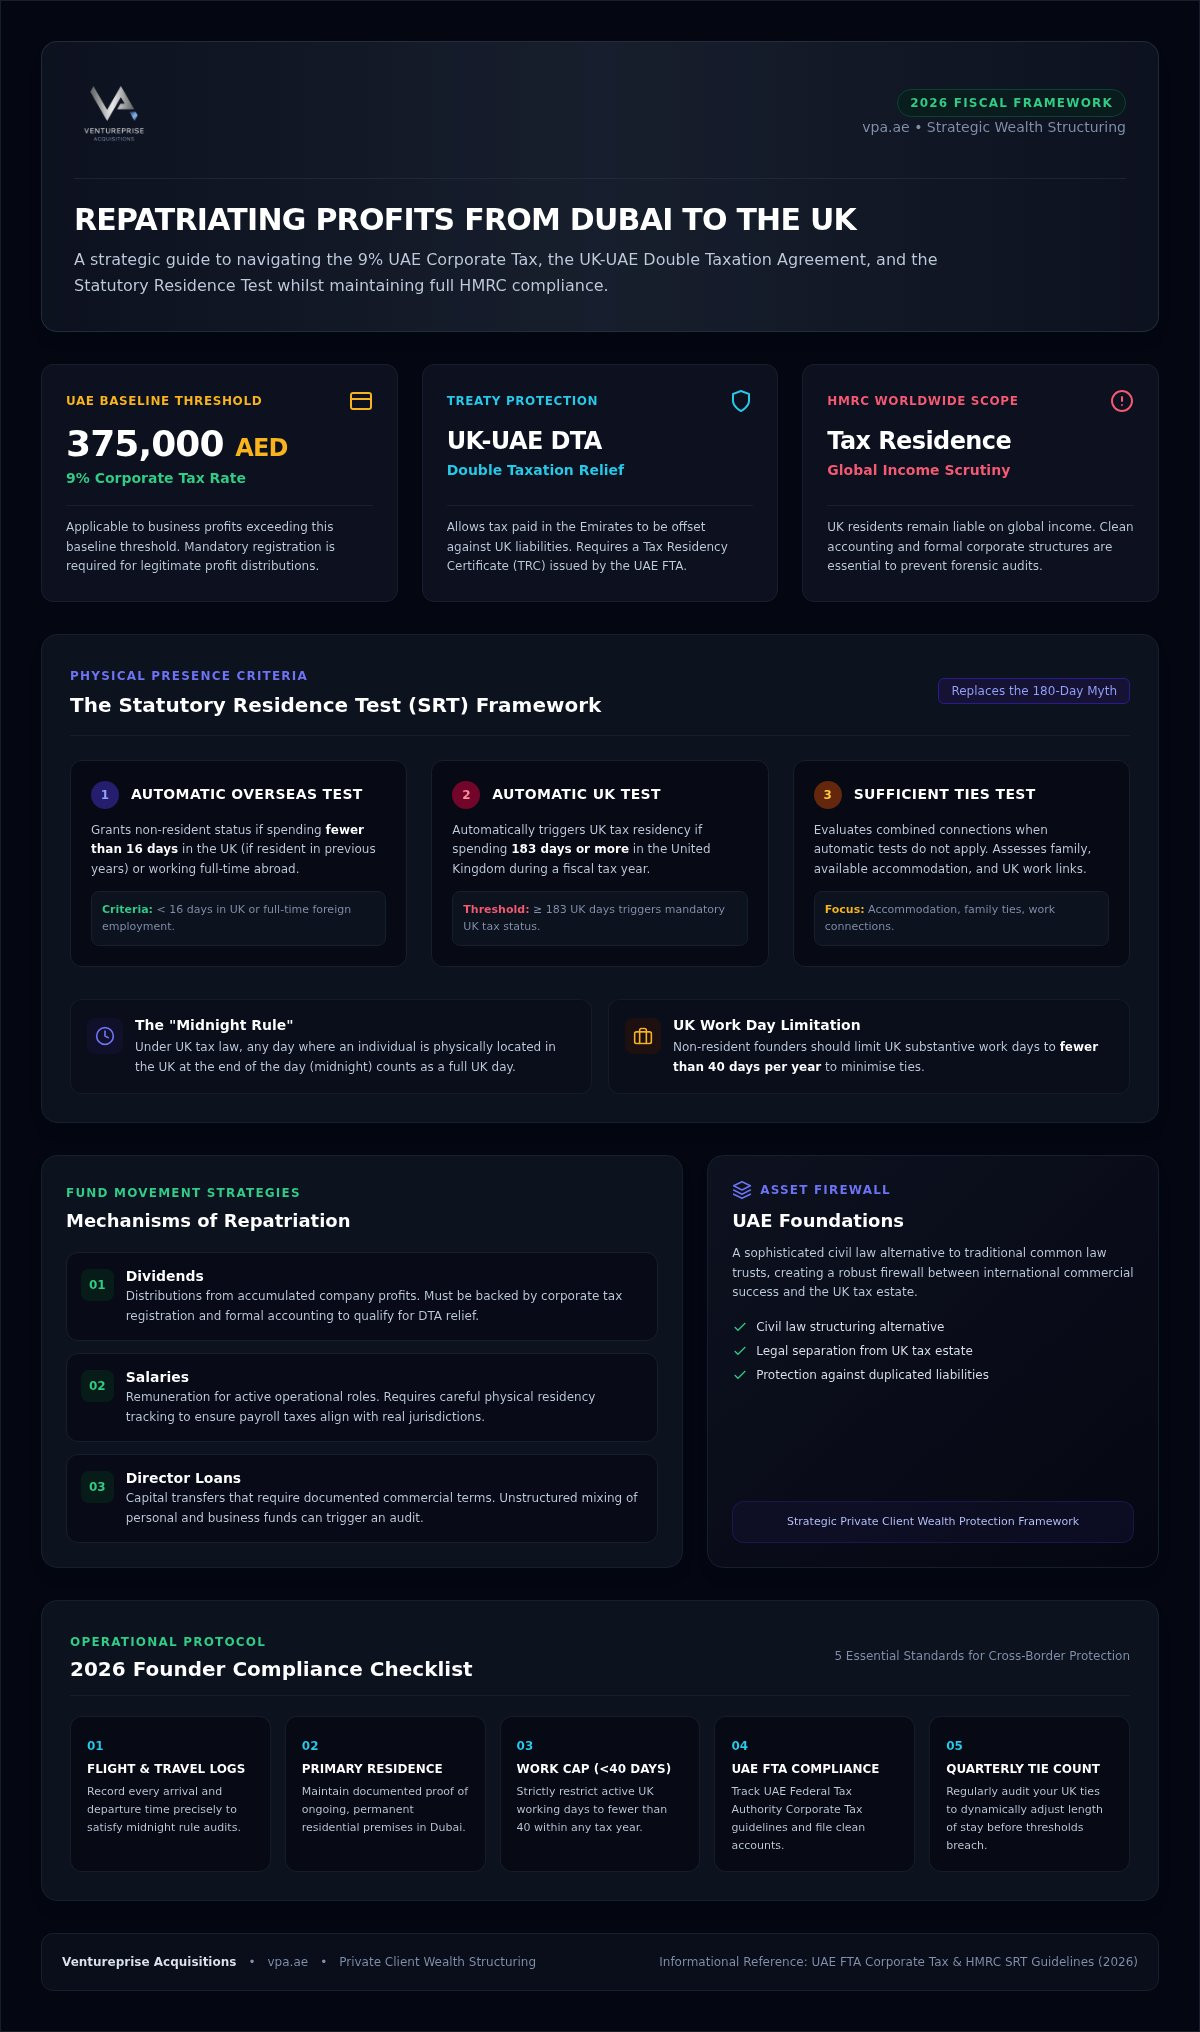
The era of the "zero-tax" myth is over. For any business generating over 375,000 AED in profit, a 9% UAE Corporate Tax rate now applies. From 2026, this threshold serves as the baseline for fiscal transparency, directly influencing how UK-resident entrepreneurs must structure their wealth to avoid duplicated liabilities. Mastering the repatriating profits from Dubai to UK tax implications is now a matter of strategic survival. To maintain your advantage, you must address three critical pillars:
The 9% corporate tax threshold of 375,000 AED
The activation of the UK-UAE Double Taxation Agreement
The acquisition of a formal Tax Residency Certificate
Whilst Dubai remains an attractive hub, the UK government's definition of "tax-free" differs significantly from the Gulf’s perspective. If you are a UK tax resident, HMRC expects a slice of your global success regardless of where the company is registered.
Understanding the UK-UAE Double Taxation Treaty
The UK-UAE Double Taxation Agreement (DTA) is your primary shield against paying twice on the same income. It provides a robust mechanism for international double taxation relief, allowing you to offset tax paid in the Emirates against your UK liability. To activate this protection, you must secure a Tax Residency Certificate (TRC) from the UAE Federal Tax Authority. This document is the only evidence HMRC respects when you claim that your profits have already been subjected to a foreign fiscal regime. Without it, you risk being taxed at full UK rates on income that has already been trimmed by the UAE’s corporate levy.
The Corporate Tax Minefield
Registration for UAE Corporate Tax is no longer a choice; it's a prerequisite for legitimate repatriation. Failing to register or maintain clean accounting records creates a "tax trap" where HMRC may classify your business distributions as taxable personal income without any relief. Mixing personal and business funds across borders is the fastest way to trigger a forensic audit. At Ventureprise Acquisitions, we focus on private client wealth structuring to ensure that every pound moved follows a compliant, documented path. Proper registration ensures that your Dubai success remains an asset, not a liability, when navigating the repatriating profits from Dubai to UK tax implications.
The Residency Factor: Why Your Physical Presence Determines Your Tax Bill
Your physical location is the ultimate arbiter of your tax liability. Whilst your business operates in the Emirates, HMRC uses the Statutory Residence Test (SRT) to decide if they can claim a portion of your wealth. Understanding repatriating profits from Dubai to UK tax implications requires a precise count of your "days in the UK". Don't fall for the "Six-Month Rule" myth; entering the UAE every 180 days might keep your visa active, but it offers zero protection against UK tax residency if your ties to Britain remain strong. Explore the Dubai company formation process to see how speed affects your tax planning.
The Three Pillars of the Statutory Residence Test
The SRT is a mechanical process designed to remove ambiguity. First, the Automatic Overseas Test can grant you non-resident status if you spend fewer than 16 days in the UK (if resident in previous years) or work full-time abroad. Conversely, the Automatic UK Test triggers if you spend 183 days or more in the country. If neither applies, the Sufficient Ties Test evaluates your family, accommodation, and work links. We help clients through strategic wealth structuring to ensure these pillars support, rather than undermine, your global goals.
Strategic Travel Planning for 2026
Success in 2026 demands a rigorous travel log. Under the "midnight rule", any day where you are in the UK at the end of the day counts toward your total. To keep your repatriation tax-efficient, follow this checklist:
Log every arrival and departure time precisely.
Maintain proof of your primary residence in Dubai.
Limit UK work days to fewer than 40 per year.
Monitor the UAE Federal Tax Authority Corporate Tax guidelines to ensure your entity remains compliant whilst you travel.
Review your "tie count" quarterly to adjust your UK stay accordingly.
By following this checklist, you can protect your wealth from the repatriating profits from Dubai to UK tax implications that catch out the unprepared. If you're unsure how your current travel pattern affects your wealth, it's time to refine your residency strategy before the next tax year begins.
Mechanisms of Repatriation: Dividends, Salaries, and Director Loans
Moving wealth across borders requires a surgical choice between salary draws and dividend distributions. Whilst a salary reduces your UAE corporate tax liability, it attracts UK Income Tax and National Insurance if you fail to meet the criteria in the HMRC Statutory Residence Test guidance. Conversely, dividends are paid from post-tax profits, offering a different profile for repatriating profits from Dubai to UK tax implications. Non-domiciled individuals residing in the UK are generally taxed on foreign dividends as they arise unless they qualify for specific transitional reliefs under the 2026 regime. Director loans offer short-term liquidity but can morph into long-term tax liabilities if HMRC classifies them as hidden distributions.
Dividends vs. Salaries: The 2026 Efficiency Comparison
A "Zero Salary" model often triggers HMRC scrutiny. They may argue the Dubai entity is a mere shell if the director isn't receiving market-rate compensation for their role. Expense rebilling allows you to move operational costs between footprints, but it must reflect genuine commercial activity to remain compliant.
Banking Logistics and Proof of Funds
UK banks frequently flag large transfers from the Middle East as high-risk. Without a clear paper trail of expense rebilling and audited financials, your funds could be frozen for months. You need a robust strategy to move operational costs between your UK and UAE footprints legally. To avoid these delays, you must establish "substance" through proper corporate governance. Explore our Dubai business infrastructure setup solutions to build the necessary framework that clears these banking hurdles. Secure your repatriation route with a strategic audit of your current banking links.
Strategic Asset Protection: Foundations and Trusts in the Repatriation Arc
UAE Foundations represent the peak of private client wealth structuring. Whilst common law trusts are standard in the UK, Foundations offer a civil law alternative with a separate legal personality. This structure provides a definitive firewall between your Dubai-generated profits and your personal UK tax estate. By decoupling legal ownership from control, you can manage your assets with 100% authority whilst ensuring that repatriating profits from Dubai to UK tax implications don't erode your capital. Proper succession planning through a Foundation ensures your wealth transfer doesn't trigger a 40% Inheritance Tax (IHT) event. You should speak to our Private Client specialists to structure your wealth before you move a single dirham.
Private Client Foundations: The Modern Entrepreneur’s Shield
Foundations allow you to maintain absolute control over your strategy whilst achieving legal separation. This is vital for navigating the UK's "Transfer of Assets Abroad" anti-avoidance legislation. HMRC uses these rules to target individuals who transfer assets to overseas entities whilst still benefiting from them. A correctly structured Foundation, managed with genuine substance, provides the necessary defence against such scrutiny. It's the elite choice for those who demand both security and agency over their international holdings.
Wealth Management and Business Growth
Your repatriation strategy must align with your end goals. Repatriating for investment in UK property requires a vastly different structure than for lifestyle spending. Property triggers specific liabilities like ATED or higher-rate Stamp Duty, which can be mitigated through professional private client wealth structuring. Whether you're funding a London residence or a global portfolio, the vehicle matters as much as the volume. We ensure your assets remain protected whilst you focus on your next phase of advancement.
Master Your Global Wealth Strategy
The landscape of repatriating profits from Dubai to UK tax implications is shifting rapidly, but it remains navigable for the prepared founder. Success in 2026 demands more than just basic compliance; it requires a proactive mastery of the Statutory Residence Test and the strategic deployment of UAE Foundations. You've built an enterprise that defies borders. Don't let outdated advice or administrative friction stall your momentum.
Ventureprise Acquisitions acts as your elite bridge between UK tax obligations and Dubai opportunities. We combine our UK roots with on-the-ground Dubai expertise to provide results-oriented, "Plain English" advisory that dismantles professional barriers. We are specialists in navigating the HMRC/UAE tax minefield, ensuring your capital remains an engine for growth rather than a target for audits. Secure Your Wealth: Contact Ventureprise Acquisitions for Expert Repatriation Strategy. Your global success deserves a structure that scales as fast as you do.
Frequently Asked Questions
What are the UK tax implications of bringing money from Dubai to the UK in 2026?
If you're a UK tax resident, you're liable for tax on your worldwide income and gains. Repatriating profits from Dubai to UK tax implications in 2026 focus on whether those funds are classified as dividends, salary, or capital. Under the new residence-based regime, the timing of your transfer and your status under the Statutory Residence Test dictate whether HMRC claims a slice of your UAE success or respects it as protected capital.
Do I have to pay tax on my Dubai salary if I am a UK resident?
Yes, UK residents must pay UK Income Tax on their global earnings, including salaries drawn from a Dubai entity. Whilst the UAE might not tax your personal income, HMRC will. You can often use the Double Taxation Agreement to offset any UAE corporate tax paid, but you'll still be liable for the difference between the UAE’s 0% personal rate and the UK’s higher tax brackets.
How many days can I spend in the UK without becoming a tax resident?
There isn't a single universal limit. Your "safe" day count depends entirely on your specific ties to Britain, such as family, work, or available accommodation. Whilst 183 days is the absolute limit, you could trigger residency in as few as 16 or 46 days if your UK connections are strong. We provide precise mapping of these thresholds to ensure your travel doesn't lead to an accidental tax trap.
Can I use a Dubai company to buy property in the UK tax-efficiently?
You can, but it's a minefield of additional costs. Holding UK residential property through a foreign company often triggers the Annual Tax on Enveloped Dwellings and higher Stamp Duty Land Tax rates. We typically advise using Private Client Foundations for asset protection instead. This provides a more robust firewall, helping you avoid the 40% Inheritance Tax event that often catches international investors off guard.
What is the 9% UAE Corporate Tax and does it affect my UK repatriation?
The UAE now levies a 9% tax on business profits exceeding 375,000 AED. This affects your repatriation strategy because it creates a formal tax footprint that HMRC recognises. By correctly registering and paying this tax in the Emirates, you can often claim relief under the Double Taxation Agreement. This prevents you from paying tax twice on the same pound of profit when moving wealth back to the UK.


Comments