

Opening a Corporate Bank Account in Dubai: The 2026 Strategic Roadmap
A Dubai bank account is not a standard service you simply apply for; it's a strategic milestone you earn by having the correct residency and corporate infrastructure in place first. Most entrepreneurs approach the process backwards, only to be met with high rejection rates or the frustrating silence of slow-moving bank managers. You're likely tired of conflicting advice regarding physical office requirements and the complexity of 2026 corporate tax compliance. For a scaling business, a dormant company without an active IBAN is a liability, not an asset.
This guide provides a blunt, results-oriented roadmap to opening a corporate bank account in Dubai without the typical bureaucratic delays. We promise to move you beyond the confusion and toward a fully functional account with low-cost international transfer capabilities whilst maintaining remote management features. We will detail the exact sequence from residency to banking activation, ensuring your business is positioned for rapid advancement in the UAE's evolving financial landscape. It's time to stop waiting for approvals and start executing your strategy.
Table of Contents
Navigating Corporate Banking in Dubai: Why Infrastructure Precedes Application
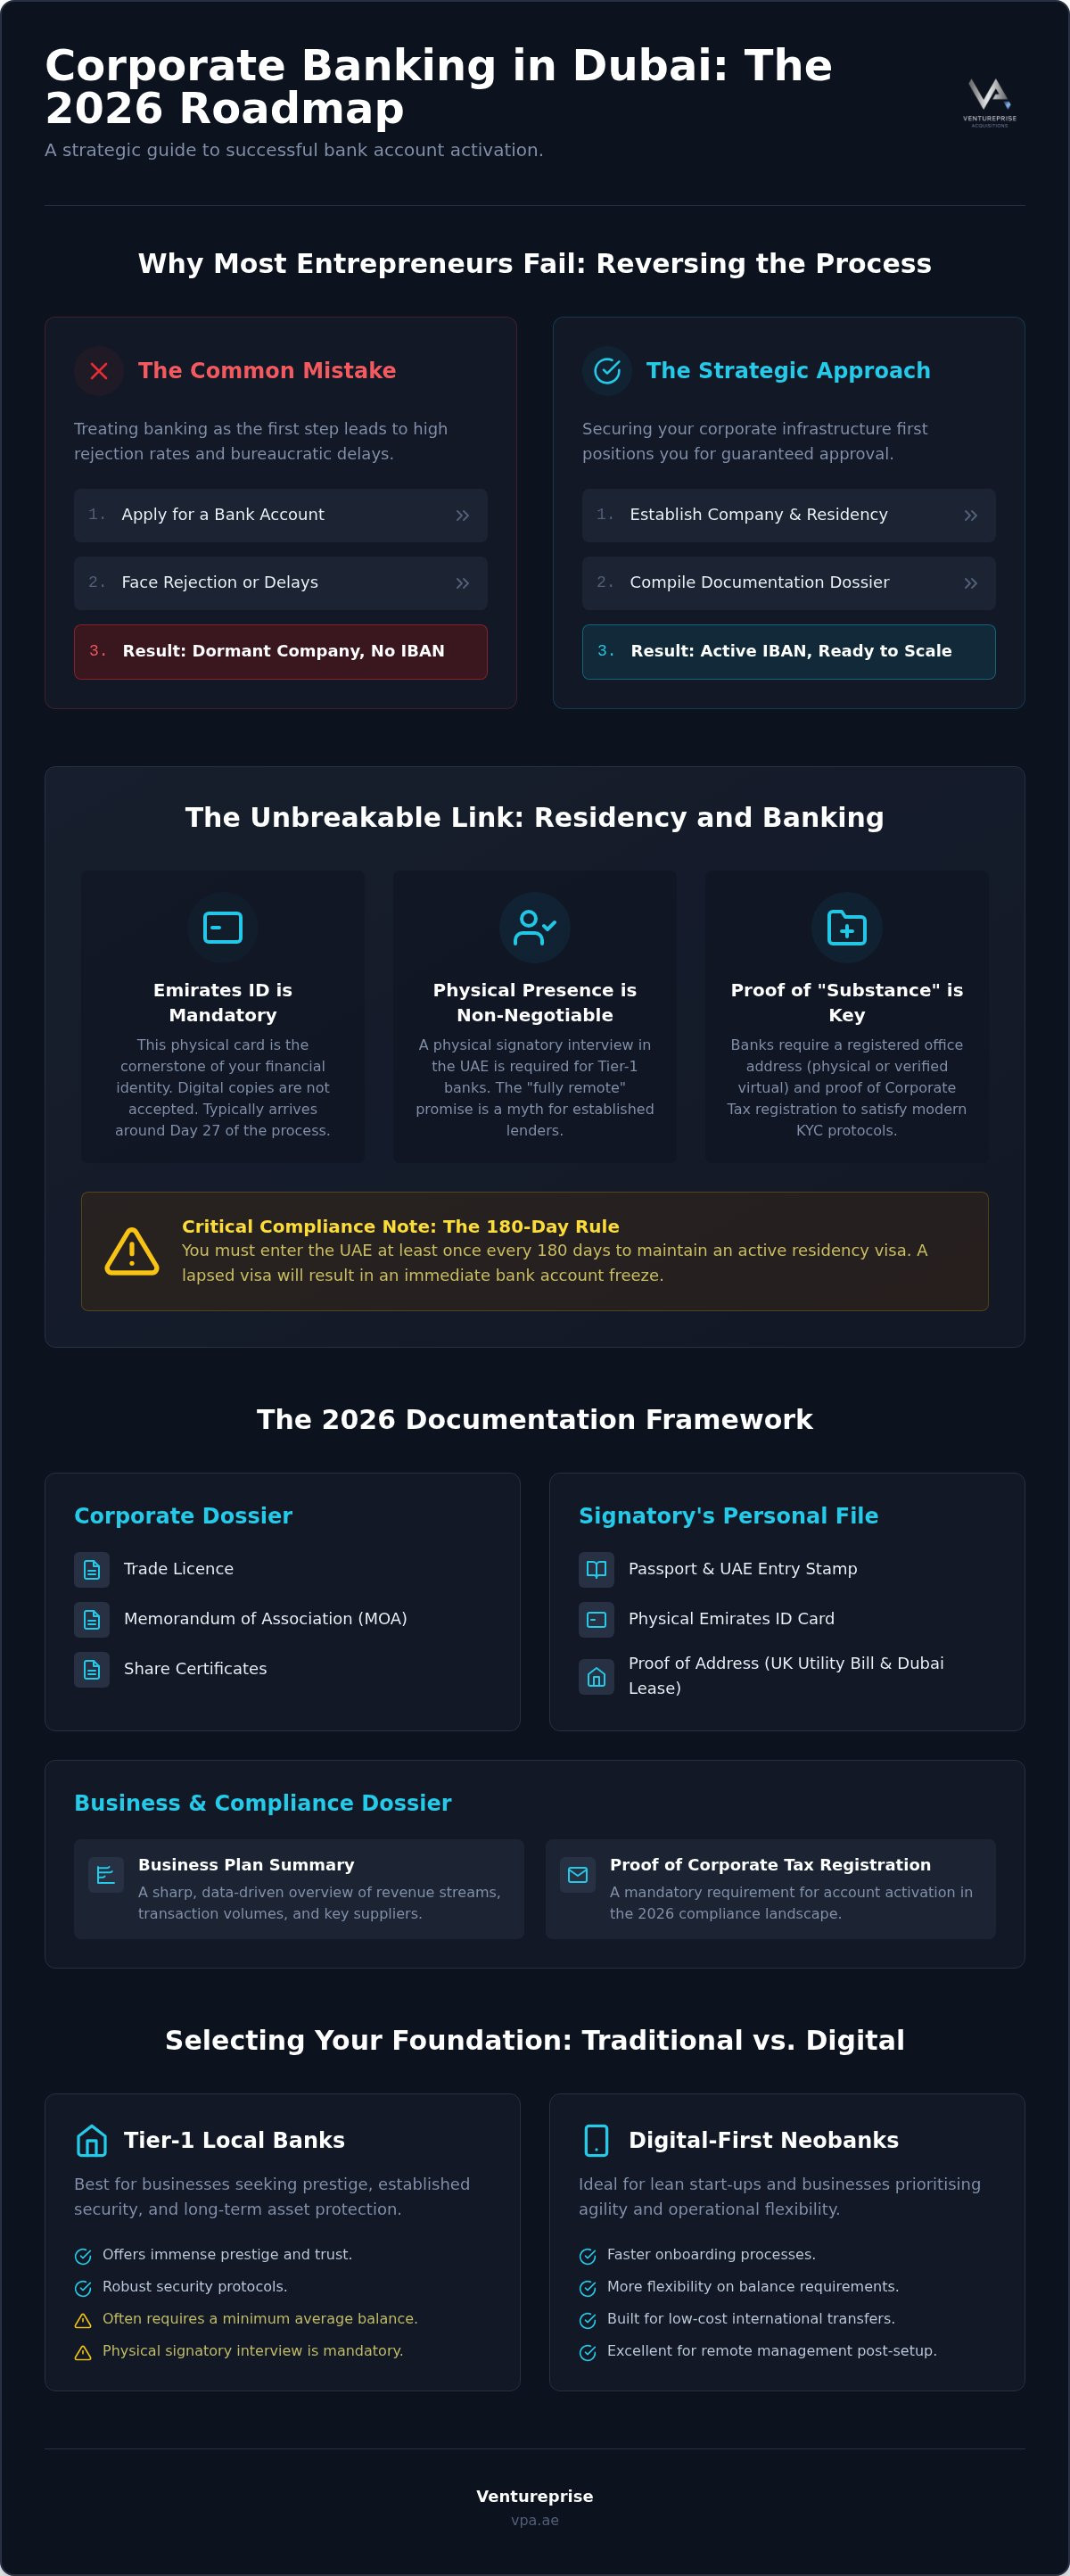
The 2026 banking landscape in the UAE has shifted from a "welcome all" approach to a rigorous, compliance-led environment. Opening a corporate bank account in Dubai is no longer a standalone administrative task; it's the final validation of your business infrastructure. Many UK entrepreneurs fail because they treat banking as step one. In reality, it's the final milestone of a successful Dubai commercial presence setup.
Whilst the initial company formation can be managed remotely from the UK, the "Remote Banking" promise is largely a myth for Tier-1 institutions. You'll need a physical signatory interview in the UAE. This physical engagement is non-negotiable for those seeking the security of established lenders. Your trade licence and residency visa are the prerequisites that prove your legitimacy to bank managers who now prioritise "substance" over simple registration.
The Residency-Banking Link
Your Emirates ID is the cornerstone of your financial identity. Without this physical card, which usually arrives around Day 27 of the formation process, your application will stall. Continuity is equally vital. You must enter the UAE at least once every 180 days to keep your residency visa active. If the visa lapses, the bank will freeze the account, halting your international transfers and local operations instantly.
The "Substance" Requirement in 2026
Banks now demand proof of a registered office address to satisfy modern KYC protocols. Whether you utilise a physical office or a verified virtual space, the bank must see a nexus between your licence and a local presence. Opening a corporate bank account in Dubai requires more than just a certificate; it requires a demonstrated commitment to the region. Mandatory corporate tax registration in 2026 adds another layer of scrutiny, as banks now verify your tax status before finalising account activation.
The 2026 Documentation Framework: Essential Requirements for Approval
Opening a corporate bank account in Dubai requires a specific documentation hierarchy. You cannot bypass these requirements if you want to avoid the high rejection rates that plague unprepared applicants. The core dossier includes your Trade Licence, Memorandum of Association (MOA), and Share Certificates. These prove your entity's legal standing and ownership structure.
For the signatory, the bank demands your passport, the UAE entry stamp from your most recent arrival, and the physical Emirates ID card. Digital copies or application receipts are insufficient. Banks also require proof of address. Often, a UK utility bill from within the last three months is requested alongside your local Dubai lease or flexi-desk agreement to establish a clear profile of the individual behind the business. By starting a company in Dubai from London, you can organise this framework before you even board a flight.
Corporate Tax and Compliance
In 2026, tax compliance is non-negotiable. Banks now mandate proof of Corporate Tax registration before an account becomes fully operational. You must also provide a Business Plan Summary. This shouldn't be an academic exercise. It must be a sharp, data-driven overview of your revenue streams, expected transaction volumes, and key suppliers. Banks use this to assess risk and determine your suitability for Tier-1 services.
Financial History vs. New Setups
Whilst you don't need personal bank statements to form your company, the bank will scrutinise your global financial footprint during the application phase. They want to see where your capital originates. You should also manage your expectations regarding balance requirements. Tier-1 institutions often require a minimum average balance, whilst digital-first alternatives offer more flexibility for lean startups. To ensure your dossier is bulletproof, you might consider scheduling a strategic review of your documentation before submission.
Traditional Institutions vs. Digital-First Neobanks: Selecting Your Foundation
Choosing the right partner for opening a corporate bank account in Dubai depends entirely on your operational scale and long-term asset protection goals. You aren't just selecting a place to store capital; you're building a financial foundation that either accelerates or bottlenecks your growth. Tier-1 local banks offer immense prestige and physical branch access, yet they often come with slower onboarding and substantial minimum balance requirements. Conversely, digital neobanks such as Wio or Zand provide rapid approvals and superior mobile interfaces, making them the preferred choice for modern SMEs.
For high-net-worth entrepreneurs, a hybrid approach is often the most strategic move. This involves utilising a local neobank for day-to-day operations whilst securing assets through a private client wealth structure. International banks like HSBC or Standard Chartered remain the gold standard for multi-jurisdictional wealth structuring, though they are notoriously selective and demand high levels of proven substance.
When to Choose a Traditional Bank
Traditional institutions remain essential for businesses requiring complex trade finance, letters of credit, or physical cheque books. If your entity handles high-turnover international trade, a dedicated relationship manager at a Tier-1 bank provides a level of bespoke service that digital platforms cannot yet match. These banks are better suited for established firms that prioritise long-term institutional stability over immediate digital agility.
The Rise of UAE Neobanking
Industry observers report that approximately 70% of new Dubai startups now opt for digital-first banking. These platforms offer seamless integration with modern accounting software and real-time VAT tracking, which is crucial for 2026 compliance. They eliminate the friction of traditional banking, allowing you to focus on market expansion rather than administrative delays. To determine which banking tier aligns with your specific business model, you can book a strategic consultation with our team.
The Ventureprise Execution: From Emirates ID to Active IBAN
Success in opening a corporate bank account in Dubai is dictated by the precision of your execution sequence. At Ventureprise Acquisitions, we dismantle the traditional 48-hour "contact" myth by replacing vague promises with a structured three-phase roadmap. Phase 1 begins whilst you are still in the UK, where we secure pre-approval for your activities and documents. This ensures your specific business model is bankable and aligned with UAE regulatory appetites before you even depart for the UAE.
Phase 2 is the "In-Country Sprint." Between Day 20 and Day 27, Ventureprise Acquisitions provides concierge support for your mandatory medical appointments and biometrics. This unlocks the delivery of your physical Emirates ID. Finally, Phase 3 involves the escorted banking interview. We leverage strategic management consulting in Dubai to ensure your corporate infrastructure passes the most stringent risk assessments.
The Banking Interview Concierge
Ventureprise Acquisitions eliminates the "middleman" delay by using direct liaison relationships with bank managers. Our team prepares you for the specific, high-level questions UAE banks ask expat founders regarding revenue origins and supplier networks. You aren't walking into a cold meeting; you're entering a pre-vetted discussion designed for approval. This authoritative approach removes the guesswork and bypasses the typical administrative friction faced by solo applicants.
Post-Activation Support
Activation is only the start. Ventureprise Acquisitions assists in setting up local SIM cards and mobile banking apps to ensure full remote management capability from London or anywhere globally. Crucially, we ensure your mandatory 2026 corporate tax registration is linked to your new account immediately. This seamless integration protects your active IBAN from compliance-related freezes, allowing you to focus on scaling your international operations without professional barriers. We also provide the necessary guidance to ensure you meet the 180-day entry requirement to keep your residency and account active.
Securing Your Financial Dominance in the UAE
Success in the Emirates requires a shift from passive application to strategic execution. You've learnt that opening a corporate bank account in Dubai is the final validation of your business infrastructure, requiring a physical presence and a robust compliance framework. Whether you choose the agility of a neobank or the prestige of a Tier-1 institution, the sequence remains the same; residency first, banking second.
We eliminate the bureaucratic friction by integrating residency and banking into a single 27-day roadmap. With UK-rooted expertise and direct liaisons on the ground in Dubai, we ensure your business model is pre-vetted for approval. Don't leave your international expansion to chance or slow-moving bank managers. It's time to secure your Dubai financial future with the specialists who get s**t done. Your vision for a global enterprise deserves a foundation that matches your ambition and delivers tangible progress. Let's build it together.
Frequently Asked Questions
Do I need to be a UAE resident to open a corporate bank account in Dubai?
Yes, whilst you can operate your business remotely, the account signatory must hold a valid UAE residency visa. This residency is the foundation of your financial identity in the Emirates. You don't need to live in Dubai full-time, but you must enter the UAE at least once every 180 days to keep the visa and account active. We integrate this residency setup into our 27-day formation roadmap.
How long does it take to get a business bank account active in 2026?
Activation typically begins from Day 27 onwards, immediately following the delivery of your physical Emirates ID. The pre-approval phase happens whilst you are still in the UK, but the final active status depends on the physical interview and document handover. Opening a corporate bank account in Dubai through a concierge-led process ensures you bypass the typical 60-day delays often experienced by those attempting the application without direct liaison support.
What is the minimum balance required for a Dubai corporate bank account?
Minimum balance requirements vary significantly based on the institution's tier. Tier-1 local banks often require a monthly average balance ranging from £10,000 to £50,000 to access premium services and relationship managers. Conversely, digital neobanks offer much lower thresholds, sometimes allowing zero-balance accounts for startups. We help you select a bank that aligns with your capital structure whilst ensuring you meet the 2026 compliance standards for your specific industry.
Can I open a Dubai bank account for my Free Zone company?
Absolutely. Free Zone companies have full access to the UAE banking system and can conduct international trade freely. Whilst Free Zone entities are popular for their 100% foreign ownership, banks will still scrutinise your substance, such as your registered office and business activity. Opening a corporate bank account in Dubai for a Free Zone entity requires the same rigorous documentation framework, including your trade licence and share certificates, as a mainland company.
Will I need to visit Dubai in person to finalise the banking process?
Yes, a physical visit is mandatory to finalise the process. Whilst we manage the initial company formation and visa processing remotely, you must travel to Dubai for a strategic Sprint between Day 20 and Day 27. During this time, you'll complete medical exams and biometrics. The bank also requires a physical interview with the account signatory to verify your identity and discuss your business model before activating your IBAN.
Is my money safe in a UAE digital neobank compared to a traditional bank?
Your capital is secure. Digital neobanks like Wio and Zand are fully licensed and regulated by the UAE Central Bank, adhering to the same stringent financial standards as traditional institutions. They offer superior digital security and real-time VAT tracking, which is essential for 2026 tax compliance. Many entrepreneurs now prefer neobanks for their agility, whilst using traditional banks for long-term wealth structuring or complex trade finance requirements.
Comments